
Programmatic Risk Management: Building Resilience in Asset Finance
In the evolving landscape of asset finance, banks, independent finance companies, and captive lenders face increasing complexities. From supply chain disruptions to regulatory changes, the need for a structured and proactive approach to risk management has never been more critical. Enter programmatic risk management - a systematic strategy that integrates risk considerations into every facet of asset finance operations.
Understanding Programmatic Risk Management
Programmatic risk management involves embedding risk assessment and mitigation strategies into the core processes of asset finance. Rather than reacting to issues as they arise, this approach anticipates potential risks and implements controls to address them proactively. This methodology ensures that risk management is not a standalone function but an integral part of decision-making across the organization.
Key Components of Programmatic Risk Management
- Integrated Risk Frameworks: Developing comprehensive risk frameworks that align with the organization's objectives and regulatory requirements.
- Data-Driven Decision Making: Utilizing advanced analytics to identify risk patterns and inform strategic choices.
- Continuous Monitoring: Implementing systems to monitor risk indicators in real-time, allowing for swift responses to emerging threats.
- Cross-Functional Collaboration: Ensuring that risk management is a shared responsibility across departments, fostering a culture of accountability.
Managing the Supply Chain
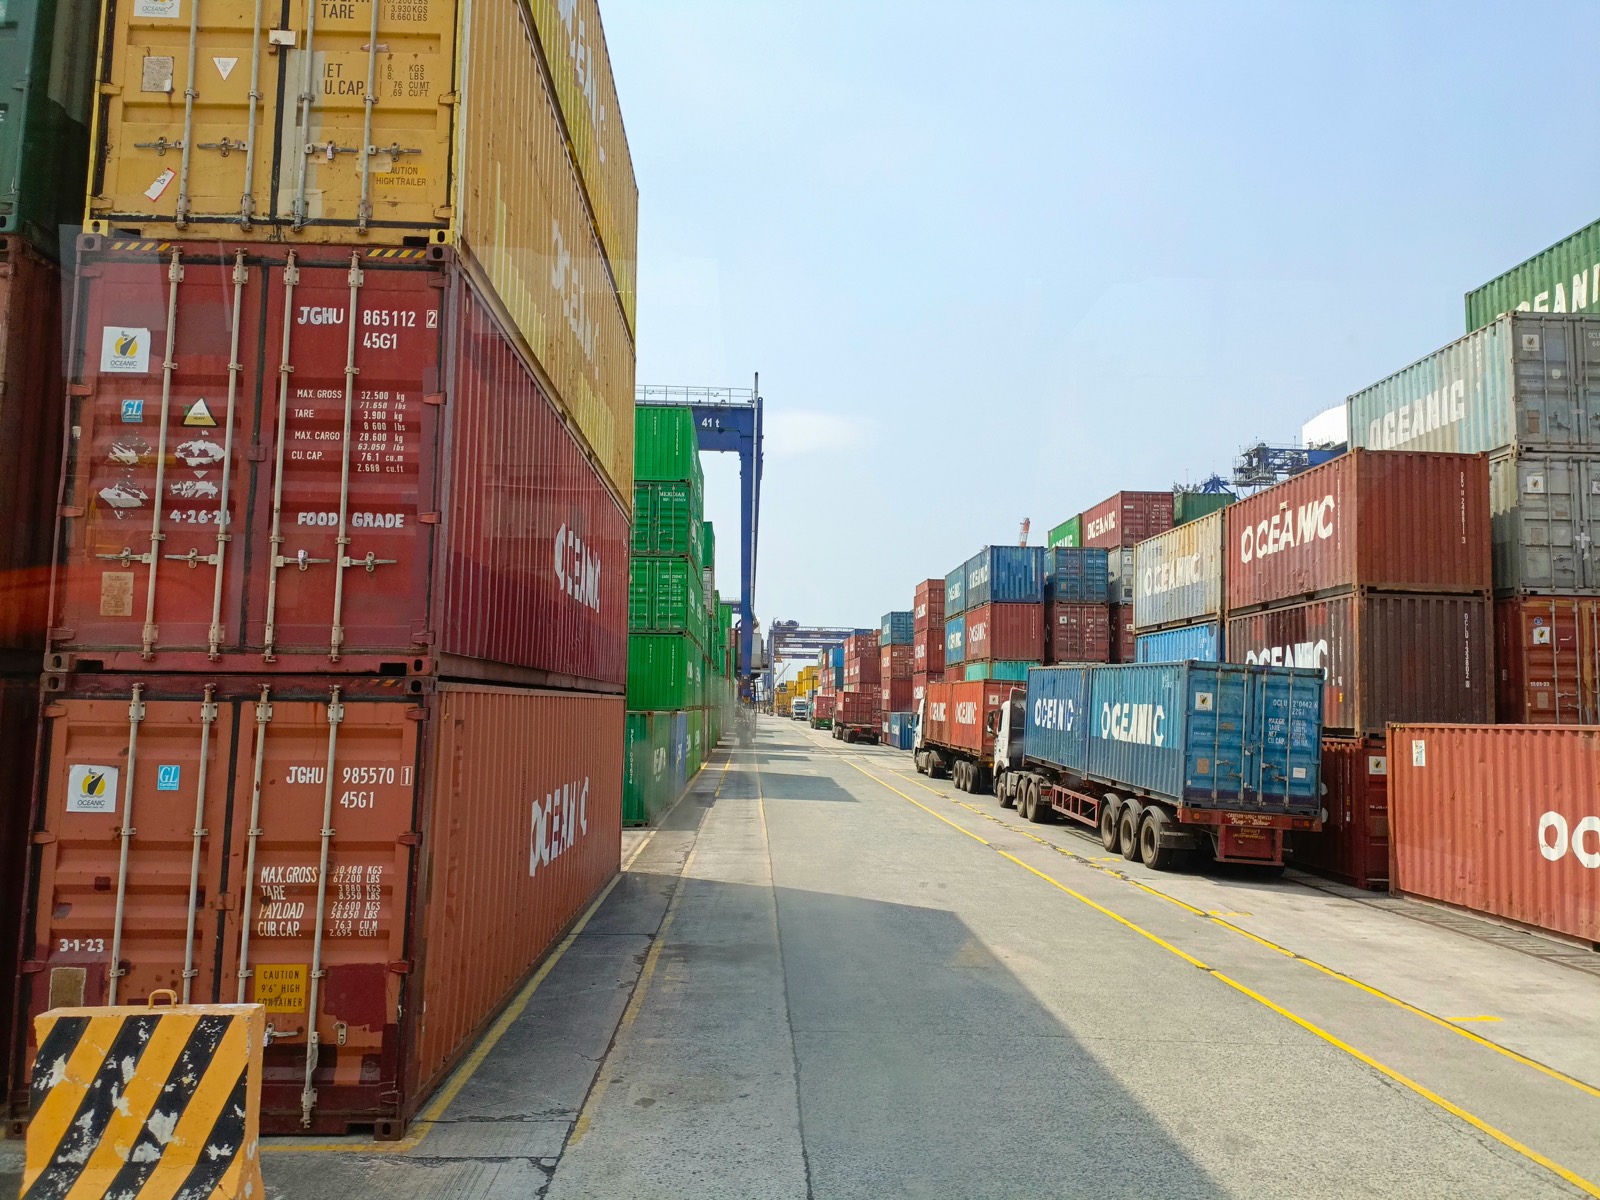
Effective supply chain management is a critical aspect of programmatic risk management. Disruptions in the supply chain can have cascading effects on asset finance operations. By integrating risk management into supply chain processes, organizations can enhance resilience and maintain continuity.
Auto Fleet Financing and Risk Management
Auto fleet financing presents unique challenges and opportunities in risk management. Factors such as vehicle depreciation, maintenance costs, and regulatory compliance require careful consideration. By adopting a programmatic approach, lenders can better assess these risks and develop financing solutions that are both competitive and secure.
Benefits of Programmatic Risk Management
- Enhanced Resilience: Organizations are better equipped to withstand disruptions and adapt to changing conditions.
- Improved Compliance: A structured approach ensures adherence to regulatory standards and reduces the likelihood of violations.
- Operational Efficiency: Proactive risk management streamlines processes and reduces the need for crisis management.
- Strategic Advantage: Organizations can leverage risk insights to make informed decisions and gain a competitive edge.
Incorporating programmatic risk management into asset finance operations is no longer optional - it's a necessity. By proactively identifying and addressing risks, banks, independent finance companies, and captive lenders can build more resilient, efficient, and competitive organizations. As the landscape continues to evolve, those who embrace this structured approach will be better positioned to navigate uncertainties and seize opportunities.
If you are looking to upgrade your business, consider contacting our team to improve how you manage your technology. We are proud to work with Sopra Banking Software to offer a comprehensive, trustworthy, and user-friendly loan management system.


' d='M11.04 19.32Q12 21.51 12 24q0-2.49.93-4.68.96-2.19 2.58-3.81t3.81-2.55Q21.51 12 24 12q-2.49 0-4.68-.93a12.3 12.3 0 0 1-3.81-2.58 12.3 12.3 0 0 1-2.58-3.81Q12 2.49 12 0q0 2.49-.96 4.68-.93 2.19-2.55 3.81a12.3 12.3 0 0 1-3.81 2.58Q2.49 12 0 12q2.49 0 4.68.96 2.19.93 3.81 2.55t2.55 3.81'/%3E%3C/svg%3E)

