
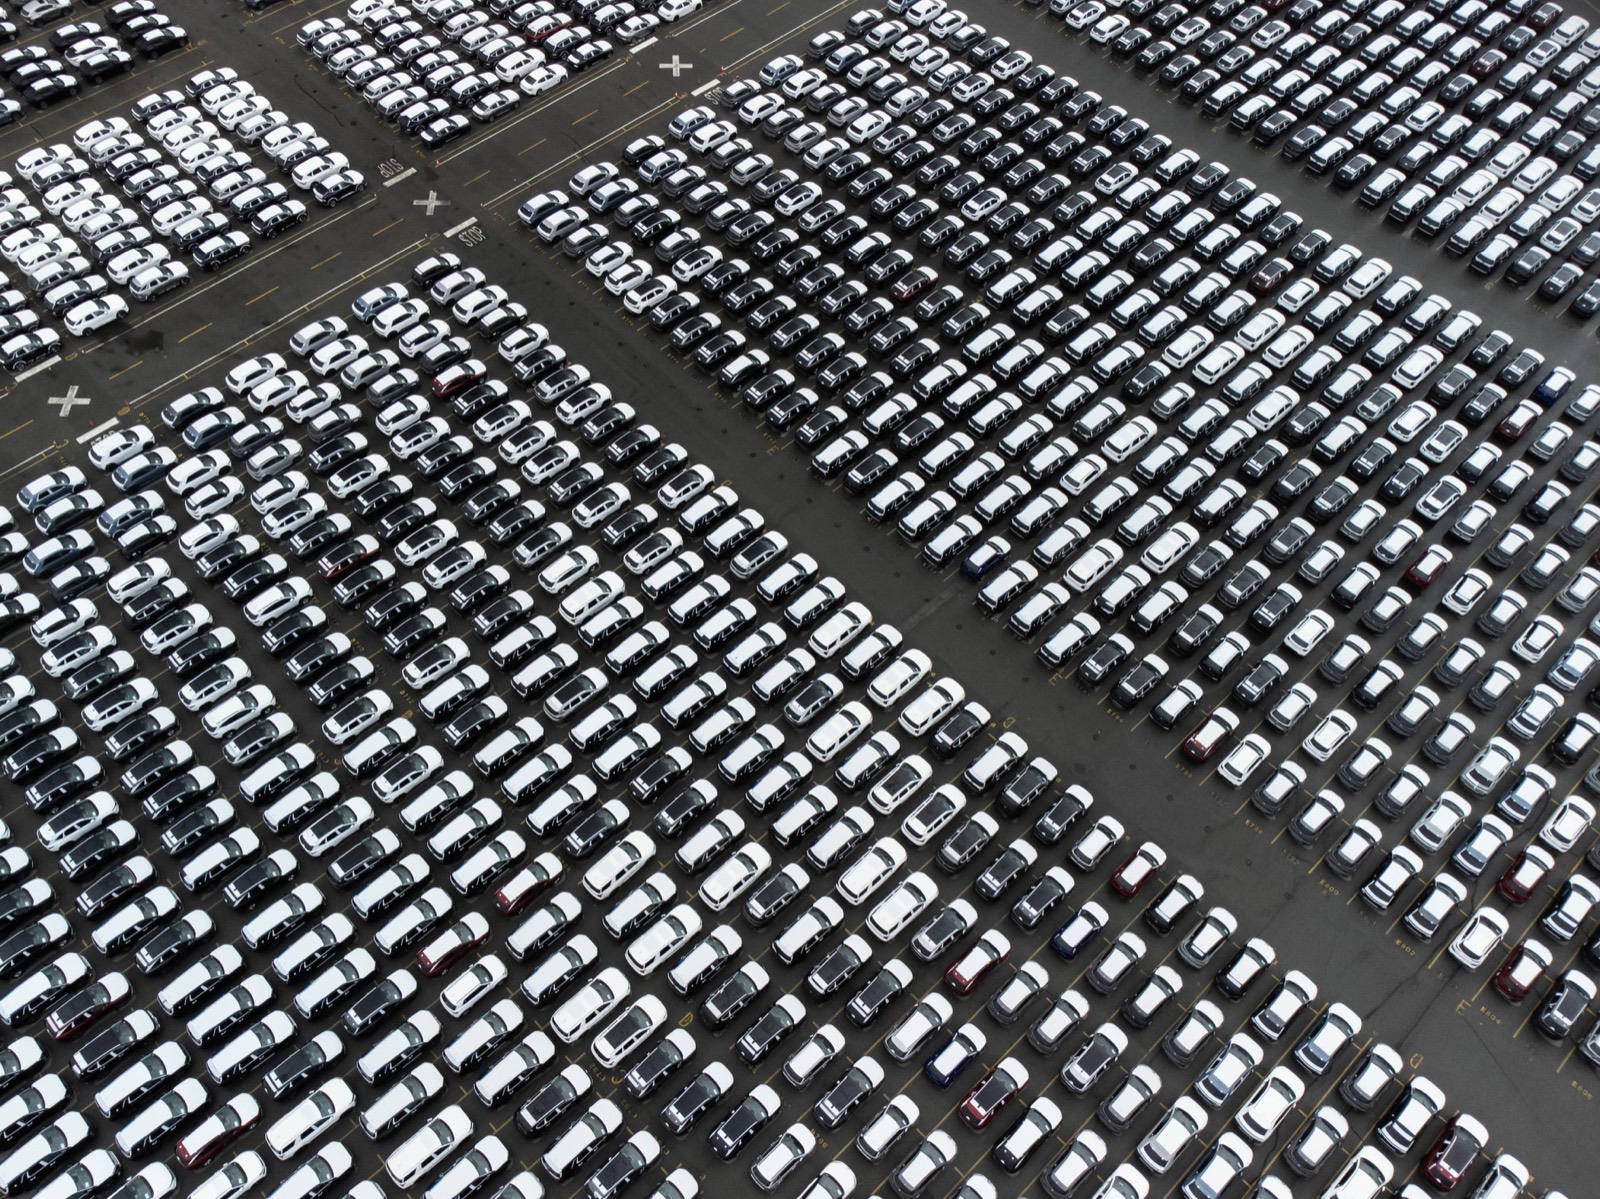
If you've ever wondered how car dealerships keep their lots full of inventory without draining their bank accounts, wholesale finance is your answer.
Also called floor plan financing or inventory financing, wholesale finance is how dealers pay for the vehicles sitting on their lot right now. The ones customers will (hopefully) buy next week, next month, or sometime this quarter.
Let's break it down without the jargon.
The Basic Concept
Here's the simple version:
A dealer wants to stock 50 cars on their lot. Each car costs $30,000. That's $1.5 million tied up in inventory before they've sold a single vehicle.
Most dealers don't have $1.5 million sitting around. And even if they did, tying it all up in inventory would be a terrible business decision.
Enter wholesale finance.
A lender (usually a bank, captive finance company, or independent finance provider) pays the manufacturer or auction house for the vehicles. The dealer gets the inventory. The lender holds the title until the car sells.
When the dealer sells a car, they pay off that specific vehicle's loan. Plus interest for however long they held it on the lot.
Simple concept. The execution? That's where it gets interesting.
How It Actually Works
Step 1: The Dealer Gets Approved
Before anything happens, the dealer needs to get approved for a wholesale credit line. This isn't like getting a consumer loan. Lenders look at:
- The dealer's financial health
- How fast they turn inventory
- Their payment history
- Current market conditions
- The types of vehicles they sell
Once approved, the dealer gets a credit line. Could be $500K, could be $10 million. Depends on the size of their operation.
Step 2: The Dealer Orders Inventory
When the dealer wants to add vehicles to their lot, they submit a funding request to their lender. This includes details about each vehicle (VIN, make, model, purchase price, etc.).
The lender reviews the request, verifies the vehicle details, checks their valuation against market data, and decides whether to fund it.
Step 3: The Lender Pays the Supplier
If approved, the lender pays the manufacturer, distributor, or auction house directly. The dealer never touches this money. The vehicle shows up on the dealer's lot, but the lender technically owns it.
The title goes to the lender. The dealer can display and sell the vehicle, but they don't own it outright yet.
Step 4: Interest Starts Accruing
From day one, the dealer is paying interest on that vehicle. The longer it sits on the lot, the more interest accumulates.
This creates a natural incentive for dealers to move inventory quickly. Nobody wants to pay six months of interest on a vehicle that's just sitting there.
Step 5: The Dealer Sells the Vehicle
When a customer buys the car, the dealer needs to pay off the wholesale loan within a certain period (usually 1-3 days).
The lender releases the title, the dealer can transfer it to the customer, and everyone's happy.
Step 6: Repeat
That credit line space is now available again. The dealer can use it to finance another vehicle. And the cycle continues.
Why Dealers Use Wholesale Finance
Cash Flow Management
The obvious one. Dealers can stock their lots without tying up all their working capital in inventory.
They can use that cash for other things like payroll, facility costs, marketing, or operational expenses.
Inventory Flexibility
With wholesale financing, dealers can respond to market demand quickly. Hot new model just dropped? They can stock up without worrying about having enough cash on hand.
Demand shifting toward SUVs? They can adjust their inventory mix without a major capital outlay.
Seasonal Management
Car sales are seasonal. Wholesale finance lets dealers ramp up inventory before busy seasons and scale back during slower periods without massive cash flow swings.
Growth Without Capital Constraints
A dealer doing $10 million in annual sales doesn't need $10 million in cash. They need a solid wholesale credit line and good inventory turnover.
This is how dealers grow their business without needing to raise massive amounts of capital upfront.
Why Lenders Offer Wholesale Finance
Secured Lending
From the lender's perspective, wholesale finance is relatively low risk. They hold the title to physical assets (vehicles) that can be repossessed and sold if things go sideways.
The collateral is liquid, trackable, and has a clear market value.
Recurring Revenue
Dealers are constantly turning inventory. Each vehicle generates interest income. A single dealer might finance hundreds or thousands of vehicles per year.
That adds up to consistent, predictable revenue for the lender.
Relationship Banking
Wholesale finance is often a gateway to other banking relationships. Once you're financing a dealer's inventory, you're in a position to offer them:
- Commercial real estate loans for their facilities
- Equipment financing for service departments
- Business checking and deposit accounts
- Payment processing services
- Retail auto loans for their customers
Attractive Yields
Wholesale finance typically offers better yields than many other forms of commercial lending. Interest rates vary, but they're generally healthy enough to make the business worthwhile.
The Challenges Nobody Talks About
Audit Requirements
Lenders need to verify that the vehicles they're financing actually exist. This means regular audits (monthly, quarterly, or triggered by specific events).
Someone physically goes to the dealership and checks VINs against the list of financed vehicles. It's manual, time consuming, and absolutely necessary.
Title Management
Managing thousands of vehicle titles is a logistical nightmare. Titles need to be tracked, stored securely, and released quickly when vehicles sell.
Slow title processing means dealers can't complete sales. That creates friction and damages the lender-dealer relationship.
Curtailment Tracking
Dealers often make partial payments on their wholesale line (called curtailments). Tracking which payments apply to which vehicles, and ensuring they're allocated correctly, gets complicated fast.
Out of Trust Situations
Sometimes dealers sell vehicles but don't pay off the wholesale loan. This is called being "out of trust" and it's a major problem for lenders.
It requires quick detection and resolution before it becomes a larger issue.
Technology Gaps
Many wholesale lenders are still running on systems built in the 1990s. Manual processes, disconnected systems, and limited automation make scaling difficult.
This is changing, but slowly.
The Modern Wholesale Finance Stack
Forward-thinking lenders are moving away from legacy systems and toward modern platforms that handle:
Digital Applications and Underwriting
Instead of paper applications and manual credit reviews, dealers apply online and get decisions faster.
Automated Funding
Funding requests get processed automatically based on predefined criteria. Fewer manual touchpoints means faster turnaround times.
Real-Time Portfolio Monitoring
Lenders can track their entire portfolio in real time. Which dealers are performing well, which ones are showing warning signs, and where the risk is concentrated.
Integrated Audits
Digital audit tools connect directly to the lender's system. Audit results flow in automatically, exceptions get flagged immediately, and reconciliation happens faster.
Borrower and Supplier Portals
Dealers log in to submit funding requests, make payments, and check their account status. Suppliers track their payments and pending transactions.
Less phone tag, fewer emails, more transparency.
Automated Communications
Payment reminders, approval notifications, and status updates happen automatically. Dealers stay informed without requiring constant manual outreach.
Who's Involved in Wholesale Finance?
The Main Players:
- Banks - Regional and national banks offering wholesale finance as part of their commercial lending portfolio
- Captive Finance Companies - Manufacturer-owned lenders (think Ford Credit, GM Financial, Toyota Financial Services)
- Independent Finance Companies - Specialized lenders focused exclusively on dealer financing
- Credit Unions - Some larger credit unions offer wholesale finance to dealer members
- Alternative Lenders - Non-bank lenders entering the space with different risk appetites
The Supporting Cast:
- Audit Companies - Third-party firms that conduct physical inventory audits
- Valuation Services - Providers of vehicle pricing data (Black Book, Manheim, etc.)
- Title Service Companies - Specialists in title processing and management
- Technology Providers - Software platforms that power wholesale lending operations
Is Wholesale Finance Right for Your Dealership?
If you're a dealer asking this question, here's what to consider:
You're a good candidate if:
- You're turning inventory regularly (60-90 days or faster)
- You have consistent cash flow and financial stability
- You want to grow without tying up all your working capital
- You can manage the administrative requirements (audits, reporting, etc.)
You might want to wait if:
- Your inventory turns slowly (120+ days)
- Your financial situation is unstable
- You're not ready for the administrative overhead
- You have irregular cash flow
Questions to Ask Potential Lenders:
- What's your advance rate? (What percentage of the vehicle's value will you finance?)
- How quickly do you process funding requests?
- What are your audit requirements?
- How do you handle out of trust situations?
- What technology do you offer dealers?
- What's your approach to title management?
- How flexible are your credit terms?
The Bottom Line
Wholesale finance is the engine that keeps dealerships running. Without it, most dealers would operate with a fraction of their current inventory, limiting selection for customers and revenue for themselves.
For lenders, it's a relationship-driven business with solid yields and manageable risk (when done right).
The dealers who succeed understand that wholesale finance isn't just about access to capital. It's about using that capital efficiently, turning inventory quickly, and maintaining strong relationships with their lenders.
The lenders who win are the ones who make the process seamless. Fast funding decisions, modern technology, transparent communication, and proactive risk management.
If you're new to wholesale finance, the concept is simple. The execution takes work. But once you understand how it works, it's hard to imagine the industry functioning any other way.
Wholesale finance, defined
Wholesale finance is a revolving line of credit a lender extends to a dealer or distributor so it can buy inventory from a manufacturer or auction and hold it until sale. Each unit on the line is collateral. The dealer pays interest and scheduled curtailments while the unit sits, and pays the unit off when it sells. In the United States the same product is usually called floor plan financing or inventory financing; in Europe it is stock financing.
Wholesale finance vs. floor plan vs. inventory finance
The three terms overlap almost completely. Floor plan financing is the dealer-side name, most common in auto, powersports, RV and marine. Wholesale finance is the lender-side and OEM-side name, and the one used for captive programs and bank divisions. Inventory financing is the broadest label and also covers non-dealer stock, such as a distributor's warehouse. If you are a lender describing your product line, you run a wholesale finance program; if you are a dealer, you have a floor plan.
Who are the biggest wholesale lenders?
Captive finance arms dominate by volume: the financing subsidiaries of the major auto, powersports, agriculture and construction OEMs. Behind them sit the large commercial banks with dealer financial services groups, then independent floor plan companies serving used-vehicle and independent dealers, and a growing set of regional and community banks running programs for local dealers. The independents and community banks are where most new programs launch, because a program can now be run on wholesale finance software rather than a large back office.
What wholesale finance software does
A wholesale finance platform handles the parts of the program that used to be spreadsheets and phone calls: funding requests and unit-level advances, curtailment schedules, aging, dealer self-service through a portal, floor audits and sold-out-of-trust detection, title and lien tracking, and real-time risk monitoring on the dealer and the inventory. VeroOS is Vero's platform for this; the wholesale finance software page walks through the full application-to-payoff workflow.
How Does Wholesale Financing Work: A Deep Dive
In the complex world of finance, wholesale finance stands out as a pivotal mechanism, especially for small and medium-sized enterprises (SMEs) looking to expand their operations without compromising their liquidity. As part of a company that's at the forefront of revolutionizing this credit product for banks, we've seen firsthand the transformative impact that wholesale finance can have on a business. Today, let's unravel the intricacies of how a wholesale loan works and its significance in the broader financial ecosystem.
The Essence of Wholesale FinancE:
At its core, a wholesale loan is a financing solution provided by financial institutions to businesses that benefit from cash upfront to purchase bulk inventory, and sell that inventory within a relatively fast period of time. From the business perspective, the interest paid is well worth gaining immediate access to cash in order to fulfill demand.
These loans are not offered directly to consumers but rather to commercial entities that then sell the inventory to end customers. Wholesale finance works by giving businesses immediate access to inventory to satisfy the demand of their consumers, while unlocking interest revenue from an asset-backed loan for lenders.
Traditionally Intense Operational Mechanics:
This credit product, while offering a favorable interest rate on an asset-backed for the lender, has traditionally been incredibly difficult to manage operationally. There are countless things that need to happen before onboarding a new business, and then the management of those clients has been enough to dissuade lenders from entering the market. Those that have, are limited in their ability to scale without technology. Title management, underwriting, actively managing the risk of existing businesses, and accounting for operational/cybersecurity risk are only a few of the reasons investment in technology is essential.
The Role of Technology in Wholesale finance:
In today's digital era, technology plays a crucial role in streamlining wholesale loan processes and reducing operational overhead. Platforms like ours leverage cutting-edge infrastructure and risk analytics to facilitate seamless transactions, risk reporting, and operational efficiencies. By enhancing the underwriting process, we ensure that our partner banks can offer competitive, yet safe, loan products to their clientele - and by automating an increasingly large percentage of operational intensity they can scale without additional headcount.
Conclusion:
Wholesale finance represents a vital cog in the financial machinery, providing an avenue for businesses to rapidly acquire capital and satisfy the demands of end-consumers. As we continue to innovate and push the boundaries of what's possible, understanding the foundational elements of products like wholesale loans is paramount in driving forward our mission to enhance banking services and facilitate growth to smaller enterprises.
If you have a portfolio and are looking to upgrade how you operate, consider contacting our team of experts today to learn more about the best technology solutions for your inventory financing needs. We are proud to work with Sopra Banking Software to offer a comprehensive, trustworthy, and user-friendly loan management system.
Demystifying Wholesale Loans: A Closer Look
Not many folks are familiar with the concept of wholesale financing or wholesale loans. In the ever-evolving financing marketplace, understanding the mechanisms behind non traditional lending models is crucial for financial institutions and their customers.
Credit Enables Commerce
Did you know that the car dealer in your hometown generally doesn’t actually own the inventory that is being marketed on their lot? Dealers of manufactured goods, whether auto, powersports, agriculture equipment, or even lawn mowers rely on external financing to fund their wholesale acquisition of inventory. Managing a dealership is a capital intensive business - particularly when your inventory runs over $10k per unit.
Giving Smaller Stakeholders a Chance Through Wholesale Loans
Wholesale loans tend to be facilitated by financial institutions (for example, regional or community banks) to businesses that operate within a radius of their physical location due to the operational complexity of running this type of loan portfolio (operations such as inventory audits have traditionally been a strain for lenders), though there are some that have networks throughout the US. There are avenues to financing through Equipment Manufacturers that offer lines of credit to dealers who hold their inventory. These lines of credit allow small-medium sized dealers to efficiently acquire their inventory, and scale their business according to demand.
Wholesale Loans Help Address Consumer Demand
Wholesale loans enable a diverse range of dealer types to operate in their respective markets to cater to the dynamic needs of their customers through providing a robust selection of inventory. Similarly, it enables lenders to access a strong rate of return on an asset-backed credit product while diversifying their loan portfolios. An enhanced relationship with local businesses can help financial institutions grow their business deposit accounts as they earn trust and build an impactful relationship with the leadership of these businesses - further unlocking potential for returns.
Wholesale Loans Leads to Deeper Customer Relationships
For banks, especially those focusing on niche markets or small to medium-sized entities, understanding and leveraging wholesale loans can open new avenues for growth and customer service. As we navigate the complexities of finance, insights into models like wholesale loans become invaluable tools for lenders. With that said, this credit product is notoriously difficult to scale as a result of operational overhead. The need to perform actions such as auditing and asset specific servicing, leave a massive need for technological advancement in this market.On the surface it may look like too much to chew as a new line of business. This is where technology focused on automation paired with lender specific workflows can massively reduce the hurdle to entry, or scale an existing business.
If you have a portfolio and are looking to upgrade how you operate, consider contacting our team of experts today to learn more about the best technology solutions for your inventory financing needs. We are proud to work with Sopra Banking Software to offer a comprehensive, trustworthy, and user-friendly loan management system.
The Evolution of Wholesale Financing in the Digital Age
The digitization of wholesale financing is profoundly changing our industry. Traditionally characterized by manual processes and face-to-face transactions, the sector is now at the forefront of financial innovation as it embraces digital transformation to enhance efficiency, accessibility, and security.
The Shift Toward Digital Wholesale Financing
The need for faster transaction times, reduced operational costs, and improved customer experience has ushered in a new era for wholesale financing. An increasing number of financial institutions leverage digital platforms and software solutions to automate operations, from loan origination to risk assessment, enabling them to serve their clients more effectively. Check out this case study as an example!
Key Tech Revolutionizing Our Industry
Several technological developments stand out for their impact on wholesale financing:
- Artificial Intelligence & Machine Learning: AI and machine learning are redefining risk assessment and decision-making in wholesale financing. By analyzing vast amounts of data, these technologies can predict loan defaults with greater accuracy, tailor financial products to individual client needs, and streamline the lending process.
- Application Program Interfaces: APIs facilitate seamless integration between different financial systems, allowing banks and financial institutions to offer a more cohesive and user-friendly experience to their clients. Through APIs, wholesale financing solutions can easily connect with accounting software, CRM systems, and other essential business tools.
Transforming Challenges into Opportunities With Digital Wholesale Financing
The digital transformation of wholesale financing is not without its challenges. Financial institutions must navigate issues related to cybersecurity, data privacy, and regulatory compliance. However, these challenges also present opportunities for innovation and differentiation in a competitive market. We work hard at Vero to minimize any additional risk of integrating with partners.
Financial institutions that leverage digital technologies can offer superior wholesale financing solutions characterized by enhanced operational efficiency, and customer satisfaction. Moreover, the adoption of digital technologies enables financial institutions to access new markets and customer segments, driving growth and profitability. All this with minimal (if any!) additional investment in headcount.
Embracing the Future
The future of wholesale financing lies in continued technological innovation. As lenders embrace transformation, we expect to see advancements in new technologies that will drive the sector towards greater efficiency.
At Vero, we are committed to leading this digital revolution in wholesale financing. By implementing cutting-edge technologies, we empower our clients with the tools they need to succeed in the rapidly evolving market.
The evolution of wholesale financing in the digital age is a testament to the sector's resilience and adaptability. As we look forward, one thing is clear: digital wholesale financing is a fundamental shift that will shape the industry.
If you have a portfolio and are looking to upgrade how you operate, consider contacting our team of experts today to learn more about the best technology solutions for your inventory financing needs. We are proud to work with Sopra Banking Software to offer a comprehensive, trustworthy, and user-friendly loan management system.


' d='M11.04 19.32Q12 21.51 12 24q0-2.49.93-4.68.96-2.19 2.58-3.81t3.81-2.55Q21.51 12 24 12q-2.49 0-4.68-.93a12.3 12.3 0 0 1-3.81-2.58 12.3 12.3 0 0 1-2.58-3.81Q12 2.49 12 0q0 2.49-.96 4.68-.93 2.19-2.55 3.81a12.3 12.3 0 0 1-3.81 2.58Q2.49 12 0 12q2.49 0 4.68.96 2.19.93 3.81 2.55t2.55 3.81'/%3E%3C/svg%3E)

